

Federal Excise Tax (FET) on trucks is a federal sales tax applied to the first retail sale of particular heavy trucks, tractors, and trailers.
If you’re a U.S. truck dealer, fleet owner, or a business that regularly purchases commercial vehicles, this tax directly affects your bottom line and compliance obligations.
Under current IRS regulations, the FET is generally 12% of the total sale price of qualifying vehicles, including any parts or accessories sold as part of the transaction (IRS Form 720 Instructions).
Filing and paying it correctly is essential because mistakes can lead to penalties, delayed sales, or audit issues that disrupt operations.
Understanding when the tax applies, which transactions qualify for exemptions, and how to file accurately can save you time, money, and unnecessary stress. This blog will break down the essentials and give you a clear path to staying compliant.
The Federal Excise Tax on trucks is part of a group of federal taxes applied to specific goods and activities. It is not a general sales tax. Instead, it targets certain high-value, high-impact transactions that have a direct link to the federal highway system.
According to the IRS, the tax applies to the first retail sale of a “highway vehicle” that meets the weight and design criteria outlined in Internal Revenue Code Section 4051. This usually means trucks, tractors, and trailers built for commercial hauling rather than personal transport.
For trucks, the IRS describes a qualifying vehicle as one “primarily designed to carry a load over public highways,” other than passengers. Tractors are classified as vehicles “primarily designed to tow a trailer or semi-trailer over public highways” (IRS Form 720 Instructions). These definitions matter because they decide whether a transaction falls under FET rules.
Understanding these distinctions helps sellers and buyers avoid costly misclassification. If a vehicle meets the IRS definition and exceeds the weight thresholds, the sale will likely trigger the 12% FET, even if the parties are unaware of the requirement.
另请阅读:了解美国通用会计准则(US GAAP)收入确认标准
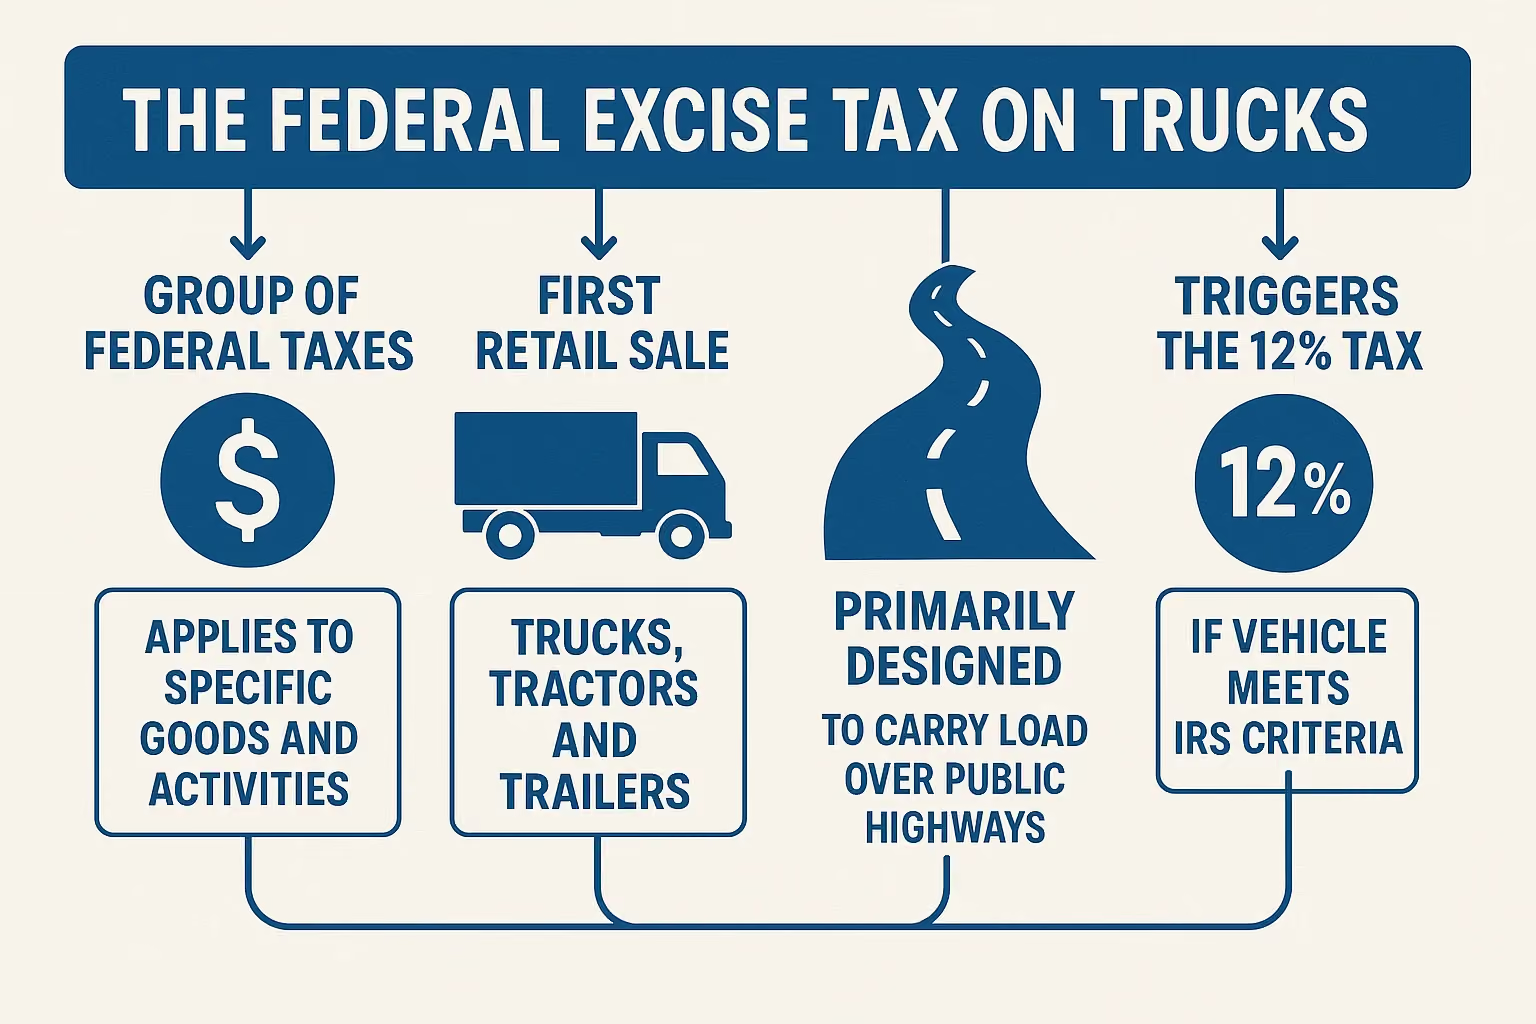
The Federal Excise Tax on trucks is part of a group of federal taxes applied to specific goods and activities. It is not a general sales tax. Instead, it targets certain high-value, high-impact transactions that have a direct link to the federal highway system.
According to the IRS, the tax applies to the first retail sale of a “highway vehicle” that meets the weight and design criteria outlined in Internal Revenue Code Section 4051. This usually includes:
These definitions matter because they determine whether a transaction falls under FET rules. Understanding them helps both sellers and buyers:
Precise classification from the start can make FET compliance much smoother for all parties involved. It also serves as the foundation for understanding the specific circumstances under which the tax must be calculated and paid.
The FET is triggered when a qualifying truck, tractor, or trailer is sold at retail for the first time. This point of sale, known as the “first retail sale,” is when the buyer takes ownership for use rather than resale. The seller is responsible for collecting the tax from the buyer and remitting it to the IRS.
申报和缴税需使用美国国税局(IRS)720号表格,即《联邦消费税季度申报表》。该表格必须与相应季度的应纳税款一并提交。准确申报对于避免罚款或处理延迟至关重要。
720号表格的季度申报截止日期如下:
专业提示:作为企业,您应注重维护清晰的交易记录,包括发票、销售单据和车辆规格说明,以支持720号表格中申报的信息。
这能确保在出现疑问时,IRS能够核实申报的准确性。持续且有条理的记录保存不仅能满足法律要求,还能让您更轻松地确定是否符合免税条件或特殊申报的考量。
了解了申报的时间和方式后,您就能更好地理解税款本身的计算方法。
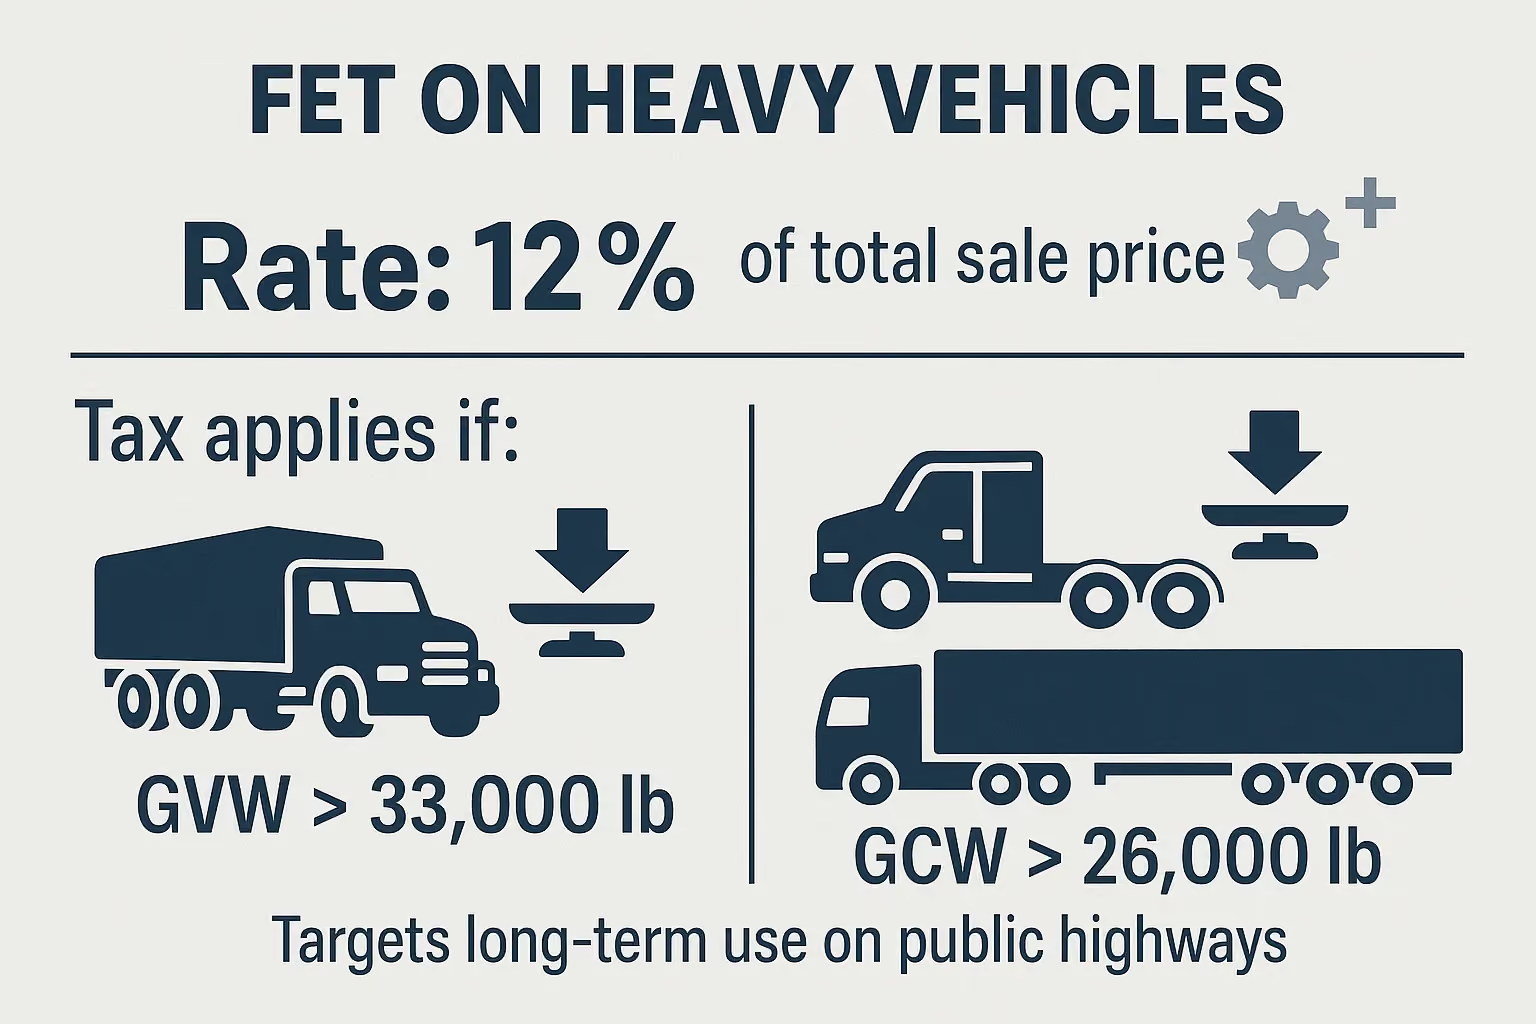
符合条件的卡车、牵引车和挂车的标准联邦消费税(FET)税率为销售总价的12%。这不仅包括车辆的基本成本,还包括作为交易一部分出售的任何零部件或配件。
重量是确定车辆是否需要缴纳联邦消费税的关键因素。该税种通常适用于以下情况:
这些阈值确保了该税种针对的是旨在长期在公共高速公路上使用的重型商用车辆。准确计算应纳税额有助于防止少缴或多缴税款。
它还能让企业识别哪些销售可能符合免税条件,从而降低成本并提高合规信心。
延伸阅读:私人有限公司注册所需文件
在大多数情况下,二手卡车的销售无需缴纳联邦消费税,因为该税仅适用于首次零售。这意味着一旦符合条件的车辆已缴纳过联邦消费税,后续的销售通常不在其征收范围内。
然而,例外情况确实存在,卖方在完成任何交易前应确认其税务状态。根据IRS 720号表格的说明,二手卡车销售在以下情况下仍可能触发联邦消费税:
即使是新车,某些交易也被排除在联邦消费税之外,例如:
明确IRS如何界定“二手”销售有助于防止意外的税务责任,并使双方在合规责任上保持一致。在理清了二手卡车销售的处理方式后,下一步是了解那些可以将特定交易完全排除在联邦消费税之外的免税条款。
卡车联邦消费税(FET)不仅仅是一项经营成本,它在资助公共基础设施方面发挥着关键作用。通过 FET 征收的很大一部分收入被拨入公路信托基金,用于支持美国公路系统的建设、维护和维修。
根据联邦公路管理局的数据,该基金有助于支付以下费用:
FET 的设计初衷是确保那些使用重型商用车(因占用更多空间而对公共道路造成更大压力)的用户,能按比例为其维护做出贡献。
了解这些资金的去向,有助于从更广阔的视角理解该税种存在的意义,以及它如何将私人运营与国家基础设施建设重点联系起来。
另请阅读:
FET 规则可能很快变得复杂,尤其是在涉及豁免、改装或高价值交易时。任何疏忽都可能导致罚款或延误。
专业的顾问可以帮助您:
如果您的业务涉及商用车销售、车队运营或出口,专业的税务指导不仅大有裨益,更能保护您的利润空间并确保合规。
保持 FET 合规不仅仅是了解 12% 的税率。这意味着您需要明确税收的适用范围、如何准确计算,以及哪些豁免条款可以合法地减轻您的税务负担。此外,这还需要清晰的文档记录和及时的申报,以确保您的业务运营不受干扰。
VJM Global 与美国企业、卡车经销商及注册会计师(CPA)事务所合作,提供以下服务:
通过将深厚的税务知识与对运营效率的关注相结合,我们助您履行义务并保护您的利润底线。
FET 通常不适用于标准经营性租赁。然而,如果租赁合同的结构在期满时实际上转移了所有权,美国国税局可能会将其视为应税销售。
可以。许多贷款机构允许将 FET 金额包含在车辆的融资方案中。这意味着买方无需一次性支付全额税款,而是通过贷款分期支付。
FET 属于联邦税,与州或地方销售税相互独立。两者可能同时适用于同一笔交易,且必须分别按照各自的规则进行计算和申报。
如果在首次零售前进行了实质性改装,其价值通常会包含在 FET 计算中。销售后进行的售后改装通常不会触发额外的 FET,但可能会影响保修或相关州法规。
美国国税局(IRS)通常在 720 表格申报之日起三年内对 FET 税务申报进行审计。若涉及欺诈或严重少报,该时效期限可能会延长。
如果销售合同解除且车辆退回,只要向 IRS 提交适当的证明文件,卖方可能有资格申请已缴 FET 的抵免或退款。




