

假设一家英国制造公司收购了一家印度贸易子公司以扩大其供应链。一夜之间,财务总监面临一个关键问题:我们现在需要编制合并财务报表吗?随着英国企业通过收购和子公司架构不断扩张,这种情况日益普遍,但许多董事对于他们在《2006年公司法》下的义务仍不确定。
合并(或集团)财务报表将母公司及其所有子公司视为单一经济实体。集团成员之间的内部交易会被抵销,从而清晰地呈现集团的整体财务状况。
根据《2006年公司法》第399条,除非符合豁免条件,否则英国母公司有法定义务在编制其个别公司财务报表的同时,编制这些合并财务报表。
本指南涵盖了谁必须编制合并财务报表、触发该要求的规模门槛、现有的豁免情况、报表必须包含的内容以及编制的分步流程。
合并财务报表结合了母公司及其所有子公司的财务结果,通过抵销集团内部交易,将集团作为一个单一的报告实体进行呈现。《2006年公司法》第399条将其定义为包含:
根据《2006年公司法》第1162条,当母公司符合以下条件时,即存在母子公司关系:
重要提示:所有权比例无需达到100%。任何层级的控制权(即使是51%)都可能构成需要合并的母子公司关系。
如果您的公司在英国注册并拥有在海外注册成立的子公司,这些实体必须包含在您的合并财务报表中。《2006年公司法》第1173(1)条将“法人团体”定义为包括在任何地方注册成立且具有独立法人资格的实体。子公司的注册地不影响此项义务。关键在于母公司是在英国注册的且行使了控制权。
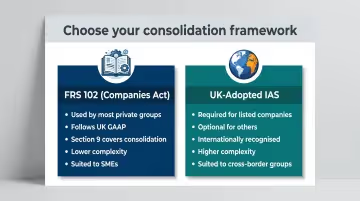
英国母公司根据其规模和市场地位在两个框架之间进行选择:
框架适用对象主要特征复杂度FRS 102(公司法)大多数私营集团遵循英国公认会计准则(UK GAAP);第9节涵盖合并报表较低——适用于中小企业英国采纳的国际会计准则(IAS)上市公司必须使用;其他公司可选国际公认;一旦采用,除非情况发生变化,否则必须持续使用较高——适用于跨国集团
无论适用哪种框架,按时提交的义务保持不变。
合并财务报表必须在以下期限内提交至英国公司注册处(Companies House):
根据《2006年公司法》第451条,未按时提交属于刑事犯罪,截止日期时在任的每位董事均需承担责任。个人处罚包括:
英国公司注册处的民事处罚也适用于公司本身,罚款金额从150英镑(逾期1个月内)到1,500英镑(逾期超过6个月)不等。
编制合并财务报表的义务直接与集团规模挂钩。根据《2006年公司法》第399条,如果集团符合“小型”标准,母公司无需编制集团合并报表。
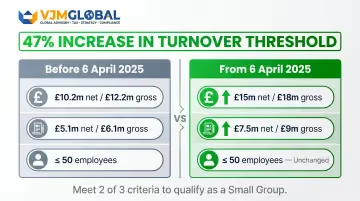
根据SI 2024/1303号法规,如果集团满足以下3项标准中的至少2项,则被视为小型集团:
标准净额数据总额数据总营业额≤ 1500万英镑≤ 1800万英镑资产负债表总额≤ 750万英镑≤ 900万英镑平均员工人数≤ 50人≤ 50人
净额与总额的区别:
之前的限额为:
这意味着营业额门槛提高了47%——此前略高于旧标准的集团现在首次获得了豁免资格。
SI 2024/1303号法规第3条提供了一个重要的捷径:集团可以将新门槛视为在上一年度即已适用。
这绕过了通常的两年资格认定规则。新符合条件的集团可以在2025年4月6日或之后开始的首个财年申请豁免,无需再等待一年来建立两年的合规记录。
通常情况下,集团必须在连续两个财政年度内符合规模标准,方可被认定为小型集团。唯一的例外是集团的首个财政年度——如果第一年即符合门槛,则可立即获得资格。
一旦获得资格,单一年份超出限额并不会立即取消豁免权。只有连续两年超出阈值,才会触发合并报表要求。
某些类型的实体无论规模大小,均无法使用小型集团豁免。如果您的集团包含以下任何一种实体,您必须编制合并报表:
注意:在 AIM 上市的公司不被视为处于“受监管市场”,如果符合规模标准,可以使用小型集团豁免。
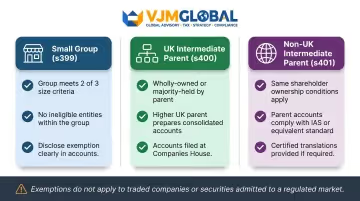
即使您的集团超过了小型集团的门槛,仍可能有三种法定豁免途径适用。
这是最常见的途径。如果您的集团在规模上符合条件且不包含任何不符合资格的实体,母公司则无需编制合并报表。
Conditions:
如果一家英国子公司本身也是母公司,且其上层英国母公司已将其纳入合并范围,则该子公司可免于编制自己的合并报表。
Conditions:
此豁免不适用于交易公司。
如果最终母公司在英国境外注册成立,则可适用类似的豁免,但需承担额外的外国集团账户备案义务。
Conditions:
此豁免不适用于在英国受监管市场拥有证券的公司。
The exemptions above apply at the parent level. Separately, FRS 102 paragraph 9.9 allows individual subsidiaries to be excluded from consolidation on specific grounds — though this does not remove the parent's overall obligation to consolidate:
Excluded subsidiaries must still be accounted for as financial instruments under FRS 102 Sections 11 and 12.
All subsidiary undertakings where the parent has control must be consolidated. Control is determined by:
This applies equally to UK and overseas subsidiaries. A UK parent with an Indian trading subsidiary and a German manufacturing subsidiary must consolidate both.
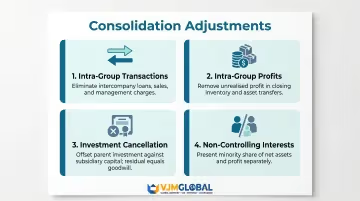
Four categories of adjustments are required to produce a true and fair group picture:
集团内部交易 — 抵销所有贷款、公司间购销以及集团实体间的管理费用,以确保仅报告外部经营活动。
集团内部利润 — 剔除母公司向子公司销售所产生的期末存货中未实现利润,并对资产转移产生的未实现收益进行调整。
投资抵销 — 将母公司对子公司的股权投资与子公司的股本及储备进行抵销,差额部分计入商誉。
非控制性权益 — 在权益项下,将少数股东应占的净资产及损益与母公司股东权益分开列示。
Goodwill arises when the purchase price exceeds the fair value of the subsidiary's net assets at acquisition. Under FRS 102:
Where the purchase price falls below fair value of net assets — known as negative goodwill or a bargain purchase — a different treatment applies:
All group entities must apply consistent accounting policies when preparing consolidated accounts. If a subsidiary uses different policies, adjustments must be made on consolidation to align with group policies. Where adjustment is impracticable, full disclosure of the inconsistency is required.
Group companies should prepare accounts to the same period-end. FRS 102 paragraph 9.16 allows subsidiaries to report up to three months before the parent's year-end if preparing to the same date is impracticable. When using different period-ends, adjust for significant transactions or events occurring between the subsidiary's reporting date and the parent's reporting date.
For groups managing complex multi-entity structures, applying these requirements consistently across jurisdictions can be challenging. VJM Global's accounting and compliance team supports UK businesses and international groups with consolidation, working across UK accounting standards and Companies House filing requirements.
With 30+ years of experience and 250+ UK businesses served, the firm draws on its global network as a member of EAI International to deliver technically compliant group accounts.
Start by collecting complete financial information from every entity in the group.
Collect individual financial statements and acquisition details:
Confirm alignment across the group:
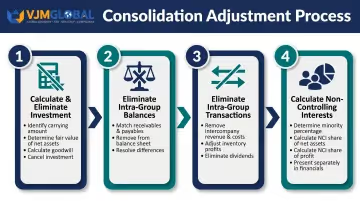
With aligned financials in hand, work through four core adjustments in sequence.
Step 1 — Calculate and eliminate investment:
Step 2 — Eliminate intra-group balances:
Step 3 — Eliminate intra-group transactions:
步骤 4 — 计算非控股权益:
调整完成后,汇总合并报表并准备报送。
需编制的合并报表包括:
所需的披露内容包括:
签署与报送流程:
该流程包括收集所有集团实体的独立财务报表,执行合并调整(抵销集团内部交易、计算商誉、确认非控股权益),并编制将集团视为单一实体的合并报表。随后,这些报表需在法定截止日期前报送至英国公司注册处。
任何拥有一个或多个子公司的英国注册母公司,若集团规模超过了《2006年公司法》第399条规定的小型集团门槛,则必须编制合并报表。无论子公司在何处注册,此规定均适用——海外子公司必须包含在英国母公司的合并范围内。
对于2025年4月6日或之后开始的会计期间,集团若满足以下三项标准中的至少两项,即被视为小型集团:总营业额净额≤1500万英镑(总额≤1800万英镑)、资产负债表总额净额≤750万英镑(总额≤900万英镑),以及平均员工人数≤50人。
是的。如果母公司在英国注册,所有子公司(无论其注册地在哪里)都必须包含在合并财务报表中。仅《财务报告准则第102号》(FRS 102)第9.9段规定的有限情况(如金额不重大、存在严重限制或持有待售)可予以豁免。
Yes. Under CA 2006 s400 (UK parent) or s401 (non-UK parent), an intermediate parent may be exempt if already included in a higher group's consolidated accounts that meet required standards and are filed at Companies House. Specific shareholder approval conditions apply depending on ownership percentage.
Companies claiming the small group exemption must state this in their accounts under s399. Those using the intermediate parent exemption must disclose the parent's name, registered office, country of incorporation (if outside the UK), and where its accounts can be obtained. Copies of the parent's group accounts must also be filed at Companies House.
Need expert support with UK consolidated accounts? VJM Global's accounting team provides comprehensive consolidation services, from technical compliance under FRS 102 to Companies House filing. Get in touch at [email protected] to discuss your group reporting requirements.




