

在并购之后难以理清会计账目?您并非孤军奋战。2024 年下半年,全球已宣布的并购交易总额达到约 1 万亿美元,创下自 2022 年初以来的最高水平,第四季度交易量接近 9,765 笔,这是自 2023 年第一季度以来未见的规模。企业合并往往会使资产、负债、商誉和非控股权益的记录方式变得复杂。
ASC 805 下的企业合并会计准则为使用收购法记录并购提供了一个框架。您需要确定收购方、计量转让的对价,并为所有已收购的资产和负债(包括您可能未曾追踪的无形资产)分配公允价值。
如果您在交易期间或交易后负责财务管理,本博客将为您揭示 ASC 805 的运作方式,帮助您掌控记账的内容、时间和方式。这一过程并不会在交易结束时停止;它还涵盖了盈利支付(earn-outs)、或有负债以及计量期间的调整。
ASC 805 规范了某一实体获得另一企业控制权的交易。它要求收购方在每一此类交易中应用收购法。该准则将“企业合并”定义为任何发生控制权转移的事件,无论是通过股权、资产购买、合同安排还是其他方式。
根据 ASC 805,美国公司必须针对被收购公司的资产、负债及任何非控股权益的确认和计量应用特定规则。ASC 805 概述了美国企业应如何处理购买法会计,包括价格分配和商誉的处理。
ASC 805 还要求收购方将任何关联交易(如或有付款或服务协议)分离开来,并在必要时单独进行会计处理。
并非所有收购都属于 ASC 805 的范畴。以下是属于排除范围的交易类型。
ASC 805 将企业合并定义为收购方获得一个或多个企业控制权的任何交易。然而,根据 ASC 805-10-15-4 及相关指南,FASB 明确排除了某些交易,并将它们归入其他 GAAP 准则下处理。这些排除项包括:
一旦交易属于 ASC 805 的范畴,一些核心要素将决定其记录方式。本节涵盖了其中最重要的部分。
ASC 805 规定了企业合并的收购法。此过程涉及多个阶段:确定收购方、确定收购日期,以及按公允价值计量转让的对价、可辨认资产、负债和非控股权益。此外,当交易不符合业务定义时,它要求确认商誉或廉价购买收益。当资产在公允价值中占主导地位时,则适用 ASC 805-50 关于资产收购的规定。
对于参与企业合并的美国公司而言,理解 ASC 805 的核心原则是必要的。该准则规范了美国公司如何对收购另一企业进行会计处理,确保所有财务方面都能得到准确报告。
并购交易框架为评估、执行和记录合并或收购提供了一种结构化的方法。它涵盖了交易策略、尽职调查、购买价格分配以及交易后的会计合规性。
应用筛选测试:如果几乎所有的公允价值都集中在单一资产或一组类似资产中,则将其归类为资产收购;否则,请验证是否存在能够产生产出的投入和实质性流程。
确定法律上的收购方,但若事实表明存在反向收购,则应适用会计收购方标准。收购日期通常与控制权转移的时刻一致,即使该日期与法律上的交割日不同。
以收购日的公允价值计量所有形式的对价,包括现金、权益工具、或有支付以及承担的负债。
应用 ASC 820 识别并计量有形资产、无形资产以及承担的负债(包括或有负债)。将剩余金额分配至商誉,或记录为廉价购买收益。
评估与前所有者或关联方的交易,以确定其是否构成业务合并的一部分,还是需要进行单独的会计处理。
将盈利能力支付(earnout)分类为负债、资产或权益,并在收购日后进行重估,将变动计入净利润。
收购方根据 ASC 718 标准承担以股份为基础的支付价值,对于存续期内的奖励,通常使用格型模型进行估值。
需注意,某些已收购的合同资产/负债仍按 ASC 606 条款处理,而租赁在分配过程中必须符合 ASC 842 的公允价值确认要求。
当交易未通过业务定义筛选时,应适用 ASC 805-50:
ASC 805 指导从业者完成从业务认定到分配及单独交易识别等关键步骤。
正确应用 ASC 805 的第一步是确定交易是否符合业务合并的条件。
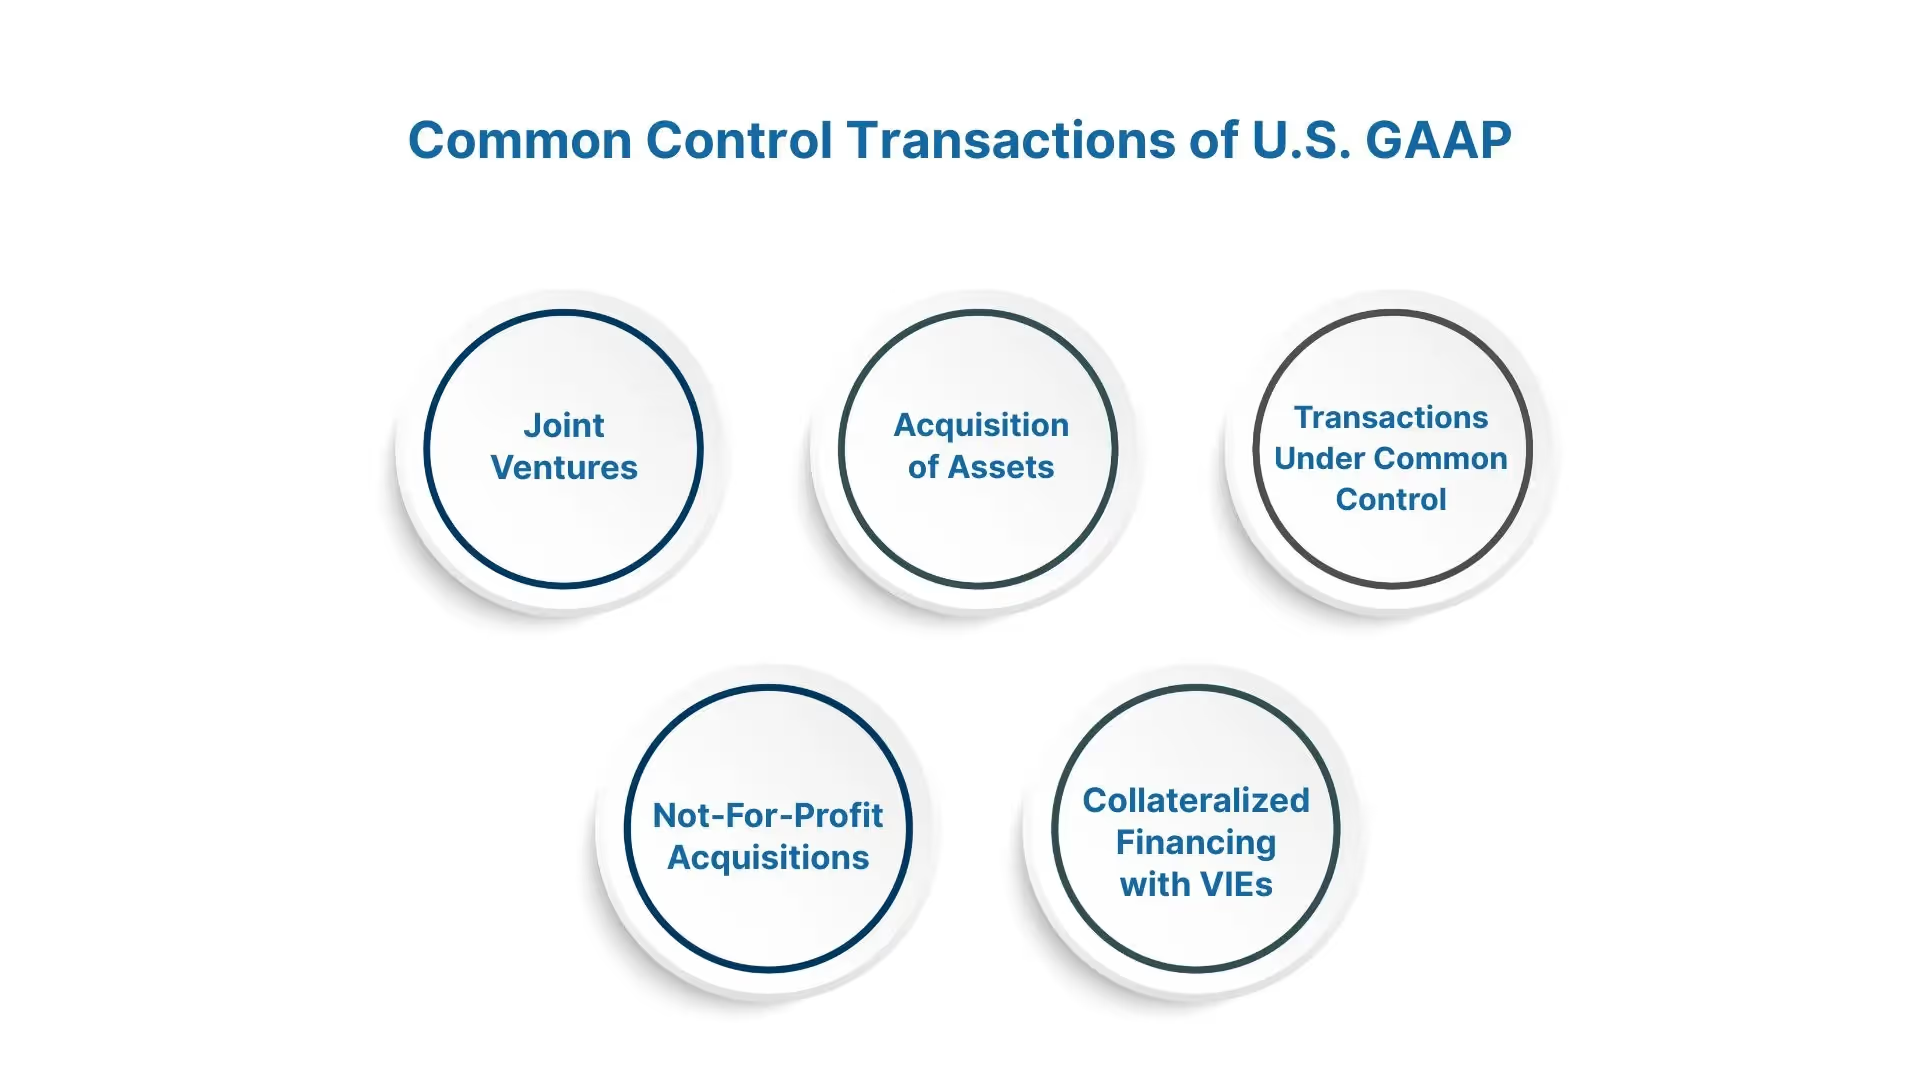
美国企业必须评估被收购公司的资产、负债和商誉,这通常需要详细的估值和会计专业知识。ASC 805 准则将几类交易排除在其适用范围之外,因为并非所有的控制权转移都符合业务合并模型:
延伸阅读:转让定价:交易净利润法
企业必须首先确定交易是否授予了 ASC 805 所定义的业务控制权。如果转移涉及资产集合、合资企业、共同控制事件、特定的非营利活动或抵押融资实体,则该准则不适用。在这些情况下,企业可能会遵循其他会计准则,即针对此类交易的专门会计规则。
区分业务收购与资产收购至关重要;以下是如何根据 ASC 805 指南做出判断的方法。
根据 ASC 805,您可以通过两步测试来确定收购是属于业务合并还是资产收购:
企业在选择会计处理方式前,必须应用 ASC 805 的两步测试。如果公允价值集中在单一资产或类似资产组上,则将其视为资产收购。如果并非如此,且该资产组包含投入以及能够产生产出的实质性过程,则应按业务合并进行会计处理。
一旦交易符合条件,即可开始会计处理。以下是如何根据 ASC 805 应用收购法。
当美国企业进行并购时,对业务合并进行会计处理对于准确的财务报告至关重要。ASC 805 要求收购方在获得另一项业务的控制权时采用收购法。从业者需遵循以下步骤:
对于分阶段收购,收购方还需对早期投资进行重新计量。伴随收购发生但服务于不同目标的交易需进行单独的会计处理。这种方法为利益相关者提供了关于收购内容及其成本的公允视角。
通过审慎地应用从估值到分离相关合同的每一个步骤,企业能够根据美国公认会计原则(U.S. GAAP)呈现透明且合规的财务结果。
VJM Global 简化了 ASC 805 的合规流程,为跨境并购提供支持,涵盖从确定收购方到记录商誉的全过程。凭借数十年的经验,我们处理购买价格分摊、公允价值评估等事务,让您能够专注于业务整合与增长。
ASC 805 指导企业在收购日按公允价值记录可辨认资产、负债、非控股权益和转移的对价。根据 ASC 805-20-25-1,收购方必须记录收购日的:
延伸阅读:FLA 申报——外国负债与资产年度申报
Next, place the consideration transferred, including cash, equity, and contingent payments, at fair value as of the acquisition date.
Then, calculate the difference:
For step acquisitions (gaining control in stages), calculate the fair value of the acquiree as a whole on the control date, then remeasure existing holdings and reflect gains or losses.
ASC 805 also permits a measurement-period adjustment (up to 1 year) to refine provisional fair values; subsequent changes adjust goodwill or gain. The residual, goodwill, or gain results from the difference between the consideration value and net assets acquired.
Some estimates require time to finalize. The next section explains the window provided by ASC 805 for updating your figures.
ASC 805‑10‑25‑15 grants acquirers up to one year from the acquisition date to finalize accounting for a business combination. During this measurement period, companies may record provisional amounts for acquired assets, assumed liabilities, transferred consideration, non-controlling interests, and preexisting equity stakes. This can only be when information is incomplete. These provisional amounts can be adjusted as more information becomes available.
When the acquirer obtains accurate data, it becomes available or proves unattainable. The measurement period ends for that item or overall, whichever comes first. ASC 805-10-55-16 requires that the acquirer adjust provisional figures when new information surfaces as if the original measurements dated to the acquisition date. Goodwill or gain and related depreciation, amortization, or earnings figures may shift accordingly.
This period exists solely under ASC 805. Asset acquisitions don’t allow provisional values; they demand complete fair-value measurements before the first post-acquisition report. Once they access reliable inputs, they adjust those items retrospectively in the first reporting period after the new data emerges.
A purchase price allocation (PPA) under ASC 805 divides the total price paid in a business combination among acquired assets and assumed liabilities, using acquisition-date fair values under ASC 820.
U.S. businesses must allocate the purchase price to the identifiable assets acquired, liabilities assumed, and any non-controlling interests. Additionally, ASC 805 dictates the handling of goodwill, which may arise from acquiring another company.
PPA also affects future reporting. Finite-lived assets get classified and amortized based on their estimated useful lives; goodwill remains unchecked for impairment under ASC 350.
Not all costs tied to a deal can be capitalized. Here's how ASC 805 treats legal, advisory, and other acquisition expenses.
ASC 805 treats acquisition-related costs separately from business combination considerations. These costs include fees such as legal, advisory, accounting, valuation, internal acquisition department expenses, and any finder’s fees. Both direct and indirect costs fall outside the calculation of purchase consideration.
Whether it’s price allocation, goodwill valuation, or preparing financial statements, working with professionals familiar with U.S. regulations and international standards can prevent costly mistakes and ensure compliance.
Under ASC 805, companies must distinguish acquisition-related costs from acquisition considerations. They must expense most costs as they arise and separately account for issuance costs per applicable GAAP. Acquirers should avoid mistakenly capitalizing legal or advisory fees within purchase price allocation.
虽然该准则提供了框架,但实施起来可能颇具难度。以下是企业在实践中常遇到的障碍。
美国企业在应用 ASC 805 时可能会遇到挑战,尤其是在企业合并过程中确定资产和负债的公允价值时。
准确的购买价格分摊对于合规至关重要,因为任何计算失误都可能导致财务报表不准确。ASC 805 下的会计处理涉及多个需要专业判断的领域,而从业者往往对其重视不足:
企业必须考虑交易结构,聘请专家进行或有事项和无形资产估值,跟踪计量期间的重新计量情况,并处理非控股权益估值中的细微差别。
每笔交易都有其独特的细微差别。以下部分涵盖了通常影响企业合并会计处理方式的因素。
顶尖的 ASC 805 指导方强调了几个影响会计结果且在常规讨论中常被忽视的交易特定因素:
收购方必须审查在交易前存在或在交易期间协商的协议,如租赁、持续供应合同或诉讼。ASC 805 规定了判断这些项目是否计入购买对价或需要单独进行会计处理的标准。
在分阶段获得控制权时,收购方必须在获得控制权时将先前持有的股权重新计量为公允价值,并确认任何相关的收益或损失。
这些“收益分成”条款需要通过判断进行分类和计量。ASC 805 要求进行初始公允价值估算,如果被确认为负债,则需通过损益进行后续调整。
企业往往低估了识别和评估无形资产(如研发项目、客户关系)以及承担的负债(如环境义务)所需的工作量。
ASC 805 允许使用公允价值法或比例法;选择哪种方法会影响商誉。关于折价或控制权溢价的判断也会发挥作用。
决定是否应用下推会计(pushdown accounting)会影响被收购方在独立财务报表中的列报与披露,但其时机和适用条件往往令人困惑。
ASC 805 允许私营企业选择替代方案:将商誉在 10 年内摊销,并根据 ASU 2014-18 简化无形资产的确认。
内部团队应尽早让估值专家参与盈利能力支付(earn-outs)和非控股权益(NCI)的计量工作。清晰的文档记录和审计准备工作能够提高透明度,并防止在复杂交易中错误应用 ASC 805。
除了基础知识外,ASC 805 还包含适用于特殊情况的条款。以下是处理这些较少见案例的方法。
缺乏内部资源来处理 ASC 805 的美国企业,通常会求助于精通美国会计准则的专业机构,以确保合规。在专业的会计支持下,企业能够从容应对企业合并中的复杂问题。从业者必须处理几个经常导致企业合并中出现意外调整的其他因素:
收购方首先要确定该交易属于应税交易还是非应税交易。在应税交易中,收购方会调增资产的税基;如果账面价值与税基存在差异,可能会产生递延所得税负债。在非应税交易中,历史税务属性(如净经营亏损 NOL 或税收抵免)会随结转税基一同转移,收购方必须评估是否需要计提估值准备。
ASC 805 将收购相关成本(如法律、估值、咨询费用)排除在购买价格之外。然而,债务或股权发行成本需遵循 ASC 320 或 ASC 825 下的美国公认会计原则(U.S. GAAP)要求。
根据 2021 年的更新(ASU 2021-08),当被收购方在收入报告中使用合同资产或负债时,收购方应根据 ASC 606 对其进行确认和计量,而非按公允价值计量。
收购方需确定或有支付款项在收购日的公允价值。如果将其归类为负债,则需在每个报告期进行重估,变动金额计入损益表。
企业通常使用多期超额收益法(MEEM)来评估商誉,并确认剩余价值涵盖了与员工相关的无形资产。
ASC 805 要求详细应用税务规则、谨慎处理交易和发行成本、准确进行合同会计处理、严谨评估或有对价,并验证商誉。公司团队必须尽早与税务顾问、估值专家及审计师协作。
根据 PCC 的指导意见,私营企业享有一定的豁免选择权。下一节将解释这些选项及其运作方式。
PCC elections enable private entities to simplify ASC 805 accounting by omitting certain intangibles and simplifying goodwill amortization and impairment. Private companies can opt into two PCC accounting alternatives under ASC 805:
Companies using this option omit separately recognizing customer-related intangible assets and noncompetition agreements unless they qualify for separate sales or licensing. Companies must apply this treatment uniformly across all eligible intangible assets if elected.
This option allows companies to amortize goodwill straight-line and restricts impairment testing to triggering events only, eliminating the second step of annual impairment evaluation. Entities may opt for this goodwill treatment even if they don’t adopt the intangible asset alternative, but embracing the latter requires also taking the goodwill option.
Firms must evaluate whether customer-related intangibles (like customer lists or contract rights) qualify for separate recognition by determining if they meet the ability-to-sell-or-license test. Even when subsumed into goodwill, those intangibles may require high-level valuation inputs, such as contributory asset charges, within valuation models for other assets.
If you’re handling a business acquisition, here’s how VJM Global can support you with the accounting, analysis, and reporting.
Mergers and acquisitions can overwhelm even experienced finance teams. You might struggle to identify the acquirer, calculate goodwill, assign fair values to assets, or handle contingent liabilities. Mistakes can snowball into audit findings or misstated reports if you're unsure how to apply ASC 805 properly. VJM Global helps you get it right the first time.
If you’re a U.S. business handling a business combination, VJM Global provides expert support in ASC 805 compliance. Here’s how VJM Global supports you through the entire accounting process for business combinations:
We handle everything from setting up opening balances to recording purchase price allocations, goodwill, and acquisition-related costs. You don’t have to manage this internally or guess at compliance.
Our team prepares supporting documentation for valuations, helps reconcile financial statements post-acquisition, and assists with ASC 805 disclosure requirements, so you're ready for internal or external audits.
If your deal involves an Indian entity, we guide you through FEMA, RBI, GST, and MCA requirements. We also ensure that all local and international reporting standards are met, especially for group consolidation.
We help you track measurement period adjustments, deferred payments, and earn-outs so your financials reflect the most up-to-date information without last-minute scrambles at month-end.
Are you planning to acquire or set up a subsidiary in India? We register entities and provide ongoing accounting support so you can focus on growth instead of paperwork.
选择 VJM Global,您获得的不仅是会计协助,更是一个深谙企业合并中技术细节与当地法规的专业团队。 立即联系 VJM Global。




