En este artículo hemos intentado analizar el concepto de factura electrónica en detalle y cubriremos varios temas, tales como: ¿cuál es la necesidad de la factura electrónica?, ¿cuál es el proceso de generación de una factura electrónica?, los beneficios del mecanismo de facturación electrónica, etc.
Uno podría preguntarse cuál es el requisito para implementar la facturación electrónica. Las facturas han sido documentos fundamentales de los impuestos indirectos desde el principio y nunca antes se había sentido la necesidad de una factura electrónica.
Actualmente, los contribuyentes utilizan diferentes programas informáticos para la generación de facturas, como SAP, Tally, Buzy, etc., y es posible que la factura generada por un sistema no pueda ser leída por otro.
Para la interoperabilidad de las facturas electrónicas en todo el ecosistema del GST, es obligatorio contar con estándares que eliminen la necesidad de volver a introducir datos.
La legibilidad por máquina y la interpretación uniforme del documento son el objetivo clave de la facturación electrónica.
Además del GST, la adopción de estándares garantizará que la factura compartida por el proveedor con su comprador, banco, agente o cualquier otra persona pueda ser leída por una máquina.
Por lo tanto, el Consejo del GST, en su 37ª reunión del Consejo del GST celebrada el 20º de septiembre de 2019, aprobó los estándares para la generación de facturas electrónicas.
2. ¿Qué es la factura electrónica?
Mito:
Sobre la facturación electrónica, existen muchos mitos en la mente de los contribuyentes, tales como que la generación de una factura a través de un software en una computadora o una máquina de punto de venta ("PoS") es una factura electrónica, o que
la factura electrónica significa generar la factura desde el portal central del departamento de impuestos.
Este no es el caso. La generación de facturas desde un portal central crearía muchas restricciones para el comercio.
La facturación electrónica consiste en la adopción de estándares para la preparación de facturas, lo que normalizará el formato en el que se compartirán los datos electrónicos de la factura con terceros para garantizar la interoperabilidad de los datos.
Los estándares no afectarán la apariencia física de la factura. Por el contrario, todos los programas informáticos adoptarán los nuevos estándares de factura electrónica, mediante los cuales realinearán su acceso y recuperación de datos en un formato estándar.
Como contribuyente, el usuario no tendrá que realizar ninguna acción. Solo será necesario que actualicen sus versiones de software para sincronizar dichos cambios en sus sistemas.
Para los pequeños contribuyentes, el GSTN ha acreditado 8 programas de contabilidad y facturación que proporcionarán un sistema básico de contabilidad y facturación de forma gratuita. Dicho software estará disponible en modo en línea (es decir, basado en la nube) y en modo fuera de línea (es decir, instalado en el sistema informático del usuario).
3. ¿Cómo funciona la facturación electrónica?
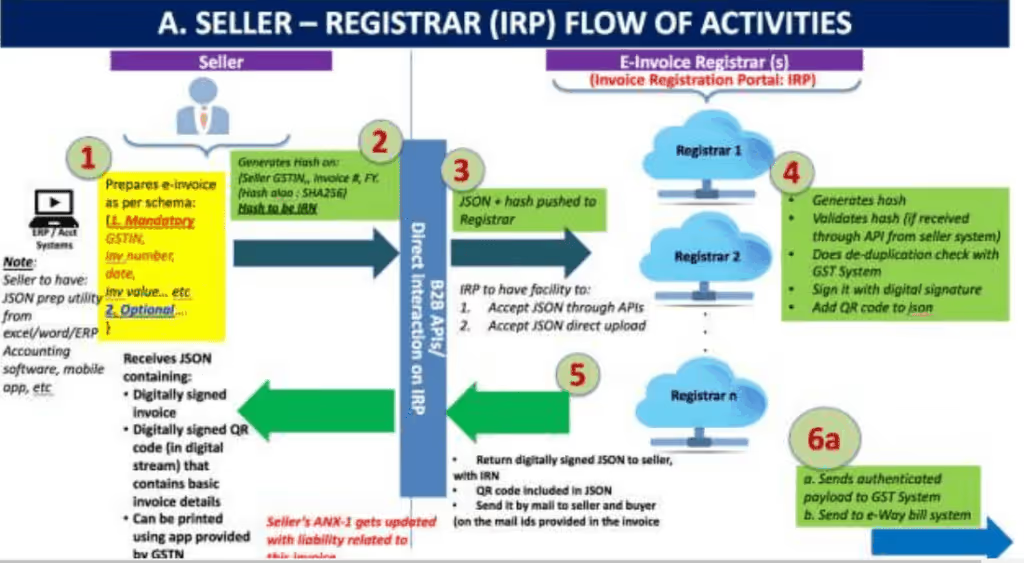
La generación de la factura electrónica será responsabilidad del contribuyente, quien deberá informar la factura al Portal de Registro de Facturas (IRP) del GST, el cual, a su vez, proporcionará un Número de Referencia de Factura ("IRN") único, la firmará digitalmente y también asignará un código QR.
El código QR contendrá parámetros vitales de la factura electrónica y será devuelto al contribuyente que la generó.
El proceso de facturación electrónica contiene 2 pasos principales:
La primera parte es la interacción entre la empresa (el proveedor en caso de factura) y el Portal de Registro de Facturas;
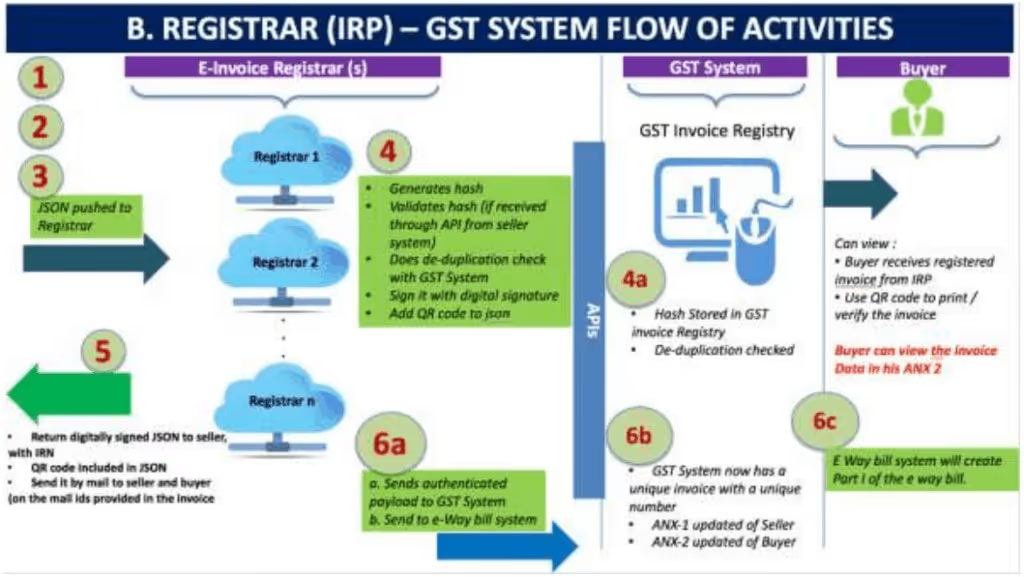
La segunda parte es la interacción entre el IRP, los sistemas de GST/E-waybill y el comprador.
Step-1: Flow of information from supplier to IRP
Supplier shall generate the invoice in his own accounting and billing software which contains all the standards notified for invoice generation. Then, Supplier’s software must be capable of generating a JSON of the final invoice or supplier can extract details of invoices in excel format and then can enter the data in "Bulk Generation Tool" provided by GSTN itself to generate JSON File that can be uploaded on IRP. Only JSON files can be uploaded on IRP.
Click here to read about process of generation of e-invoice| User Manual
Supplier shall generate a unique Invoice reference number (“IRN”) (known as “Hash” in technical term). This is an optional step. Supplier can generate IRN and upload it alongwith Invoice data. IRN shall be based on 3 parameters namely:
GSTIN of supplier
Invoice Number
Financial year to which invoice pertains
Supplier shall upload the JSON generated of final invoice alongwith IRN, if generated. Uploading can be done directly on IRP or through GSPs or through third party provided applications.
IRP shall validate the hasp uploaded by supplier alongwith JSON file or will generate the hash if it not already generated.
IRP shall check the hash from the Central Registry of GST system to make sure that same invoice pertaining to same supplier for same Financial year is not uploaded again.
Upon validation form central registry, IRP shall add its digital signature to JSON file and also will add QR code to the JSON file. The QR code will contain GSTIN of seller and buyer, Invoice number, invoice date, number of line items, HSN of major commodity contained in the invoice as per value, hash etc.
The hash computed by IRP will become the IRN (Invoice Reference Number) of the e-invoice. IRN shall be a unique number for each invoice for entire financial year.
Then step 2 will start with sharing of data with GST and e-waybill system.
Step:2 Flow from IRP to GST System/e-waybill system & buyer
IRP shall share the signed copy of e-invoice data alongwith IRN, QR code and digital signature to the GST system as well as e-waybill portal.
Using such shared information, GST system shall update the ANX-1 of supplier and ANX-2 of buyer, which in turn shall determine the liability and ITC.
E-waybill system shall generate the part-A of e-waybill using such data and supplier/buyer will be required to update only Vehicle number in Part-B.
Notes:
E-invoicing standards shall contain some mandatory information and some option items. System shall not accept the electronic invoice unless all the mandatory information is available. Optional information may be used by supplier as per their business requirements.
Supplier may send his data for registration of invoices to more than one registrar. However, IRP shall carry out a de-duplication check and will make sure that only one IRN is allotted to a invoice. Therefore, is same invoice is uploaded at multiple IRPs then system will generate only one IRN and will reject other requests.
QR code shall enable a quick review, validation and access of the invoices from the GST system.
4. What are the benefits of E-invoicing?
This concept makes e-invoices completelyinter-operable eliminating transcription and other errors.
It provides better taxpayer service as uponuploading electronic invoice, system will automatically update ANX-1, ANX-2 andpart-A of e-waybill. It will reduce the duplication of efforts and will alsoautomate the process of reconciliation.
Complete trail of B2B invoices will reducepossibility of tax evasion.
Elimination of fake invoices will increaseefficiency of tax administration.
5. Turnover Limits for Einvoicing.
E-invoice has been implemented in a staggered manner based on aggregate turnover of person. Following is the date of applicability of e-invoice on different class of taxpayers:
Class of taxpayer
Date of applicability of e-invoice provisions
Legal reference
With aggregate turnover of more than INR 500 crores during any preceding Financial year from 2017-18 onwards*
* Earlier, e-invoice was made applicable based on aggregate turnover in Financial year. However, vide Notification No. 70/2020-Central Tax dated 30.09.2020, aggregate turnover was to be considered for any preceding financial year from 2017-18 onwards.
6. Which Class of persons are exempted from generation of e-invoice?
As per Notification No. 13/2020-Central Tax dated 21st March, 2020, following class of persons are not required to generate e-invoice irrespective of their turnovers:
Special Economic Zone Unit
Insurance Company, Banking Company, Financial Institutions and Non-Banking Financial institutions
Goods transport agencies
Person providing passenger transport services
Person providing service of admission to exhibition of cinematograph films in multiplex screens
7. What type of documents is required to be reported to GST System?
As per Notification No. 13/2020-Central tax dated 21st March, 2020, eligible persons should generate e-invoice with for every supply of goods or services or both to registered persons or for export. Therefore, E-invoicing is required for following documents:
Tax Invoice issued to registered person
Credit Note by supplier issued to registered person
Debit note by supplier to registered person
Invoice issued for export of goods or services (with or without payment of GST)
Invoice issued for supply of goods or services to Special Economic Zone (with or without payment of GST)
Invoice issued for deemed export
Any other document as required for supply of goods or services to registered persons.
8. Whether any uploading is required for B2C transactions?
As per notification no. 14/2020- Central Tax dated 21st March, 2020, In case of supply of goods to unregistered person by the person whose turnover exceeds INR 500 crores during any preceding Financial year from 2017-18 onwards then such person is required to generate QR Code for such B2C Invoice.
Such QR code is not generated through e-invoicing portal rather same is generated by supplier himself. Further, if supplier provides any other QR code for payment purpose, such as QR code for payment through paytm or UPI, then such QR code shall be considered as valid for GST purpose. However, If payment is made after some time of generation of Invoice then QR code generated for payment shall not be considered as valid and supplier will be required to create a separate QR Code for such invoice.
9. Direct generation of invoice on Invoice Registration Portal (IRP)
Some peopleare of the opinion that e-invoicing shall facilitate the generation of invoiceon government’s tax portal. This is a myth and taxpayer shall continue togenerate invoice from their respective accounting software. However, smalltaxpayer may use one of the eight emplaned software to generate invoices.
10. What will be the format of Unique Invoice Reference Number (IRN)?
The unique IRN will be based on GSTIN ofgenerator of document (invoice or credit note etc.), Year and Document numberlike invoice number. The hash could also be generated by the taxpayers based onabove algorithm.
Accordingly, one can pre-generate and printhash on the invoice book, however, the same will not make the invoice validunless it is registered on the portal along with invoice details.
Further, The hash algorithm that is to beused by the taxpayers has been specified in the e-invoice standard that ispublished. The hash will be the IRN.
To ensure duplication check, the registrarwill be required to send the hash to Central Registry of GST System to confirmwhether the same has been reported already. In case it has been reported byanother registrar and the Central Registry already has the same IRN, then theregistrar will reject the registration and inform the sender. Only uniqueinvoices from a taxpayer will be accepted and registered by the registrar.
11. What is the use of Digital Signing by e-Invoice Registration Portal?
IRP (Invoice Registration Portal) shall generate a hash to verify the invoice or use the hash submitted with invoice data and then will digitally sign such invoice with the private key of the IRP.
The IRP will sign the e-invoice along with hash and the e-invoice signed by the IRP will be a valid e-invoice and used by GST/E-Way bill system.
12. What is the use of QR Code on electronic invoice?
The IRP shall generate a QR code containing the unique IRN (hash) along with some important parameters of invoice and digital signature so that it can be verified on the central portal as well asby an Offline App.
This will be helpful for tax officers tocheck the invoice on the roadside where Internet may not be available all thetime.
The QR code will consist of the followinge-invoice parameters:
GSTIN of supplier
GSTIN of Recipient
Invoice number as given by Supplier
Date of generation of invoice
Invoice value (taxable value and gross tax)
Number of line items.
HSN Code of main item (the line item havinghighest taxable value)
Unique Invoice Reference Number (hash)
13. How verification of the invoice will be done through QR Code?
An offline app will be provided on the IRP to authenticate the QR code of the invoice offline and its basic details. However, to see the whole invoice, one will have to connect to the portal and verify and see the details online.
The facility to download entire invoice will be provided to tax officers, the way it is currently available under E-way bill system.
The facility of QR code verification will be made available only through GST System and not IRP. This is because the IRP shall store the invoice for next 24 hours only. In order to achieve speed and efficiency, the IRP will be a lean and focused portal for providing invoice registration and verification service, IRN and the QR codes. Hence, storing of the invoices will not be a feature of the IRP.
14. What is the Difference between QR Code affix on B2B Invoices and B2C invoices?
QR Code on B2B invoices is generated by e-invoice portal along with IRN and digital signature. Therefore, same can be verified through QR code scanning app provided by GSTN. Through scanning QR Code, app will verify that whether QR Code is valid or not.
However, QR Code on B2C invoices are generated by supplier himself and same can't be verified through app provided by GSTN. Purpose of enabling QR Code on B2C invoices is to promote digital payment.
15. Frequently asked questions on e-invoice
15.1 What is the time limit of generation of e-invoice?
As such there is no time limit is given under GST law for generation of e-invoice. Further, no validation is also created on e-invoice portal for document date.However, as per Rule 48(4) of CGST Rules, all eligible class of persons are required to upload detail of invoices on e-invoice portal and invoice shall be issued after generating an Invoice reference number. Any invoice issued without IRN shall be considered as invalid.
P. ej.
Date of generation of Invoice
Date of Generation of IRN
Date of supply of goods
Legal status
1st March, 2021
1st March, 2021
1st March, 2021
Such movement of goods shall be considered as valid as goods are moved under a valid tax invoice, i.e, Invoice with IRN
1st March, 2021
2nd March, 2021
1st March, 2021
Even though e-invoice portal shall not restrict the generation of e-invoice on 2nd March, 2021. However, when goods are moved on 1st March, 2021 with a invalid invoice then such movement shall be considered as without invoice and goods can be detained for such non-compliance.
15.2 Whether persons with aggregate turnover of less than INR 50 Crores can create e-invoice on optional basis?
No. Facility to generate e-invoice is available for persons aggregate turnover of more than INR 50 Crores. E-invoice portal shall allow to create login credentials to such person whose aggregate turnover exceeds INR 50 crore in GST returns. However, if portal doesn't allow to create login credentials then supplier is required to enable e-invoice facility against his GSTIN. While enabling e-invoicing, declaration is required to be given that aggregate turnover of supplier exceeded INR 50 crores during any of the preceding year from 2017-18 onwards.
15.3 whether persons selling through e-commerce platform is required to generate e-invoice?
If aggregate turnover of any seller exceeds INR 50 crores during any of the preceding year from 2017-18 onwards then he is required to generate e-invoice. No specific exemptions are given for persons selling through e-commerce operator. Therefore, they are required to generate e-invoice if above mentioned condition are fulfiled.
15.4 Similar to waybill, Whether recipient can generate e-invoice instead of supplier?
No. Only supplier can generate e-invoice.
15.5 Whether e-invoice is applicable on supplies covered under RCM?
Yes. If supplier is registered under GST and supplying any goods or services which covered under RCM and condition of aggregate turnover is satisfied then supplier is required to generate e-invoice. However, if recipient is generating self-invoice for transactions liable to RCM then no e-invoice is required.
15.6 Which year is to be considered for checking aggregate turnover of INR 50 Crores of preceding year?
Each year from F.Y. 2017-18 onwards are to be considered. If aggregate turnover during any year exceed INR 50 crores then supplier is required to generate e-invoice.
CA Kapil Mittal
Socio con más de 20 años de experiencia asesorando a empresas en expansión global, creación de entidades, estructuración transfronteriza, fiscalidad internacional y cumplimiento normativo en más de 60 jurisdicciones.