Presentación de la declaración GSTR-8: Fecha límite | Elegibilidad y normas

Publicado el:
February 11, 2020

Tabla de contenido

Hable con nosotros
¡Gracias! Hemos recibido su envío.
¡Vaya! Algo salió mal al enviar el formulario.

Una firma,
soluciones globales

Apoyamos los negocios internacionales con confianza y claridad.
Agendar una llamada

The GSTR-8 is a TCS (Tax collected at source) deduction form. The e-commerce companies, registered under the GST regime, file GSTR-8 return for every month. This form contains all the details of supplies made through e-commerce platforms (to both registered and unregistered customers) and TCS amount collected with respect to such supplies. 

Along with that, the form also contains details of the consumers, payable tax, and paid tax amount. Under section 52 of Central Goods and Service Tax Act, 2017 (“CGST Act”), GSTR-8 filing is mandatory for registered e-commerce operators because, under the same law, the e-commerce platform is defined as a place that different vendors and customers use for receiving and supplying goods or services to the online market. 

Furthermore, it's compulsory for the e-Commerce operator to register under the GST regime and get registration from the tax collection source. 

1. Who comes under the tag "e-commerce operator"?

Well, e-commerce operators are the persons who manage or own a digital platform like Flipkart or Amazon, etc. E-commerce operators provide a platform where sellers can reach out to a large number of consumers. On the other hand, customers can get to see multiple items from multiple sellers at a competitive price. 

2. Salient Features of the GSTR-8 Return Form

  1. Every e-commerce operator, registered under GST regime must file the GSTR-8 return
  2. GSTR-8 must be filed on or before the 10th of the following month of a certain tax period
  3. Part D of GSTR 2A contains all the details of GSTR-8, filed by the e-commerce operator.
  4. The e-commerce portal deducts TCS from the supplier of goods and services and deposits the same amount to the Government
  5. The e-commerce operators deduct 1% of TCS on all the goods and services sold out through the portal

3. Why GSTR-8 Return Filing is important?

As you already know that GSTR-8 shows all the details of the supplies made through e-commerce platforms and the total amount collected on such supplies. The TCS provisions came into the role from the 1st of October 2018. Once TCS starts being applicable, now suppliers can take the input credit of all those TCS deducted by the e-commerce operator, after filing GSTR-8 return. 

For example, suppose X Enterprise is a garment supplier and sales garments of Rs. 30,000 through the e-commerce platform Amazon. Now, being an e-commerce operator, Amazon will deduct 1% TCS and deposit Rs. 300 to the Government. This amount worth Rs. 300 will reflect in the GSTR-2A of X Enterprise after Amazon files GSTR-8.

4. Eligibility & due dates

All c-commerce operators registered under the GST regime are eligible and must file the GSTR-8 for every month by 10th of the following month, 

Example

‍

Return Monthly Due Date
January 2020 10th February 2020
February 2020 10th March 2020
March 2020 10th April 2020
April 2020 10th June 2020

‍

5. Late payment fee of GSTR-8 & penalty of missing the due date

If an e-commerce operator fails to file the GSTR-8 within due date, then a penalty of Rs. 100 for CGST and Rs. 100 for SGST will be levied per day. Hence the total amount will be 200 per day (maximum Rs. 5000). No late fee is applicable to IGST delayed filing.

Along with the penalty fee, 18% interest per annum is also required to be paid. The taxpayer needs to calculate the total taxable amount by counting the time period between the due date and the actual date of GSTR-8 filing.

6. Prerequisites for filing GSTR-8 Return

In order to file the GSTR-8, below mentioned details are mandatory to provide.

  • You have to be a registered taxpayer under the GST regime and have to have a GSTIN consists of 15 digit PAN
  • The yearly aggregate turnover of your business should be 20 lakh rupees or greater than that (Rs. 10 lakhs in the North East States)
  • You have to have an online marketplace where other companies or traders register and sell goods or services to customers
  • All registered taxpayers, who have neither opted for the composition scheme nor have a Unique Identification Number (UIN) are eligible to get the return. For the non-resident taxpayers, this return is not applicable
  • You have to keep a track on all the tax collected at source by you for the transactions that are carried out through your e-commerce platform.
  • If in case any incorrect information is filed in GSTR-8 then same can be rectified in GSTR-8 of succeeding months.
  • Rectification can be made by the due date of GSTR-8 of September month of the financial year or date of filing of Annual return, whichever is earlier.

7. What are the details e-commerce operators need to furnish while filing the GSTR-8 Return?

Year-Month(Period): Choose the year and month from the drop-down menu, for which month of which year, you're filing GSTR-8

7.1 Tabla 1 y 2: Detalles básicos

El GSTIN, el nombre legal y el nombre comercial de la persona registrada se completarán automáticamente una vez que el contribuyente inicie sesión utilizando el portal de GST.

7.2 Tabla 3: Detalles de los suministros realizados a través de un operador de comercio electrónico

Tabla: 3A. Suministros realizados a personas registradas

  • Aquí, el contribuyente debe proporcionar los detalles de los suministros realizados a través del portal de comercio electrónico a personas registradas (B2B).
  • Proporcione los detalles del proveedor registrado que suministra bienes o servicios a clientes registrados utilizando el portal de comercio electrónico.
  • Se debe indicar el GSTIN del comerciante, el valor bruto del suministro total, el valor del suministro devuelto y el importe neto sujeto a impuestos.

3B. Suministros realizados a personas no registradas

  • Los suministros realizados a través de la plataforma de comercio electrónico a contribuyentes no registrados deben mencionarse aquí.
  • El operador de comercio electrónico debe completar los mismos campos, como el GSTIN, el valor bruto del suministro total, el valor del suministro devuelto y otros impuestos.

‍

7.3 Tabla 4: Modificaciones a los detalles de los suministros respecto a cualquier declaración anterior

4A. Suministros realizados a personas registradas

Si un operador de comercio electrónico necesita modificar algún detalle de las transacciones B2B del mes anterior que se presentaron en la Tabla 3A, puede editar los detalles en esta parte del formulario de declaración GSTR-8.

4B. Suministros realizados a personas no registradas

Del mismo modo, si se requiere alguna modificación en los detalles de las transacciones B2C, el contribuyente puede editarla en esta sección.

‍

7.4 Tabla 5: Detalles de los intereses

  • Si se produce algún retraso en el pago del TCS recaudado, aquí encontrará la sección de intereses. Debe ingresar el importe de los intereses a pagar por el depósito tardío.

‍

7.5 Tabla 6: Impuestos a pagar y pagados

  • Aquí debe proporcionar los detalles relacionados con el importe total del impuesto a pagar bajo CGST, SGST e IGST. Además, debe mencionar el importe del impuesto que ha pagado hasta la fecha.

‍

‍

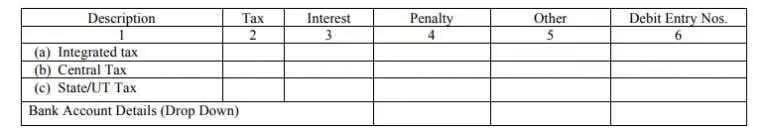
7.6 Tabla 7: Importe de los intereses a pagar y pagados

La CBIC aplica un interés del 18% sobre el importe del impuesto a pagar si hay algún retraso en el pago. Si en su caso existe algún retraso, debe ingresar el importe de los intereses que debe pagar por ello en la columna correspondiente de la tabla 7.

‍

‍

7.7 Tabla 8: Reembolso reclamado del libro mayor de efectivo electrónico

  • Cualquier reembolso reclamado del libro mayor de efectivo electrónico se informará aquí.

‍

7.8 Table 9: Debit entries in cash ledger for TCS/interest payment [to be populated after payment of tax and submission of return]

  • Post submission of return, The final field will also get auto-populated  Which shows cash ledger used for payment of TCS/Interest Payment.

‍

Every compliance is a must and missing any deadline not only imposes a penalty but also results in legal action. So be a tax compliant. To know more about the different types of GST returns, deadlines and the frequency of filing, read our article on GST Returns.


CA Sachin Jindal
Explore las perspectivas, consejos y actualizaciones de expertos del CA Sachin Jindal
Conozca más sobre el autor

Blogs recientes

