

The GSTR-8 is a TCS (Tax collected at source) deduction form. The e-commerce companies, registered under the GST regime, file GSTR-8 return for every month. This form contains all the details of supplies made through e-commerce platforms (to both registered and unregistered customers) and TCS amount collected with respect to such supplies.
Along with that, the form also contains details of the consumers, payable tax, and paid tax amount. Under section 52 of Central Goods and Service Tax Act, 2017 (“CGST Act”), GSTR-8 filing is mandatory for registered e-commerce operators because, under the same law, the e-commerce platform is defined as a place that different vendors and customers use for receiving and supplying goods or services to the online market.
Furthermore, it's compulsory for the e-Commerce operator to register under the GST regime and get registration from the tax collection source.
Well, e-commerce operators are the persons who manage or own a digital platform like Flipkart or Amazon, etc. E-commerce operators provide a platform where sellers can reach out to a large number of consumers. On the other hand, customers can get to see multiple items from multiple sellers at a competitive price.
As you already know that GSTR-8 shows all the details of the supplies made through e-commerce platforms and the total amount collected on such supplies. The TCS provisions came into the role from the 1st of October 2018. Once TCS starts being applicable, now suppliers can take the input credit of all those TCS deducted by the e-commerce operator, after filing GSTR-8 return.
For example, suppose X Enterprise is a garment supplier and sales garments of Rs. 30,000 through the e-commerce platform Amazon. Now, being an e-commerce operator, Amazon will deduct 1% TCS and deposit Rs. 300 to the Government. This amount worth Rs. 300 will reflect in the GSTR-2A of X Enterprise after Amazon files GSTR-8.
All c-commerce operators registered under the GST regime are eligible and must file the GSTR-8 for every month by 10th of the following month,
Example
If an e-commerce operator fails to file the GSTR-8 within due date, then a penalty of Rs. 100 for CGST and Rs. 100 for SGST will be levied per day. Hence the total amount will be 200 per day (maximum Rs. 5000). No late fee is applicable to IGST delayed filing.
Along with the penalty fee, 18% interest per annum is also required to be paid. The taxpayer needs to calculate the total taxable amount by counting the time period between the due date and the actual date of GSTR-8 filing.
In order to file the GSTR-8, below mentioned details are mandatory to provide.
Year-Month(Period): Choose the year and month from the drop-down menu, for which month of which year, you're filing GSTR-8
GSTIN、登録者の正式名称および商号は、納税者がGSTポータルにログインすると自動的に入力されます。
表:3A. 登録者への供給
3B. 未登録者への供給

4A. 登録者への供給
電子商取引事業者が、表3Aで申告した前月のB2B取引詳細を修正する必要がある場合、GSTR-8申告フォームのこのセクションで詳細を編集できます。
4B. 未登録者への供給
同様に、B2C取引の詳細に修正が必要な場合も、納税者はこのセクションで編集できます。


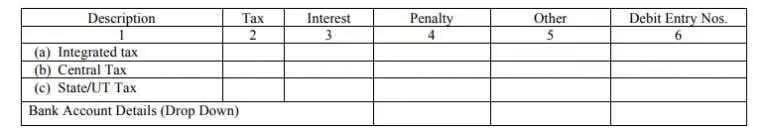
CBIC(中央間接税関税委員会)は、税金の納付に遅延があった場合、支払うべき税額に対して18%の利息を課します。遅延が発生した場合は、表7の列に支払うべき利息額を入力してください。


Every compliance is a must and missing any deadline not only imposes a penalty but also results in legal action. So be a tax compliant. To know more about the different types of GST returns, deadlines and the frequency of filing, read our article on GST Returns.




